
What Can You Actually Get for $400 to $600 a Month at Coulter Nissan?
It's the question every car shopper asks before they ever walk onto a lot: what does my monthly budget actually get me? A $400 to $600 payment sounds simple until you start factoring in term length, down payment, interest rate, and trade-in value, all of which can push the same car from one end of that range to the other. Here's a realistic look at what falls into that window right now, and what moves the needle if you want more car for the same payment.
The Sweet Spot: New Sentra and Kicks
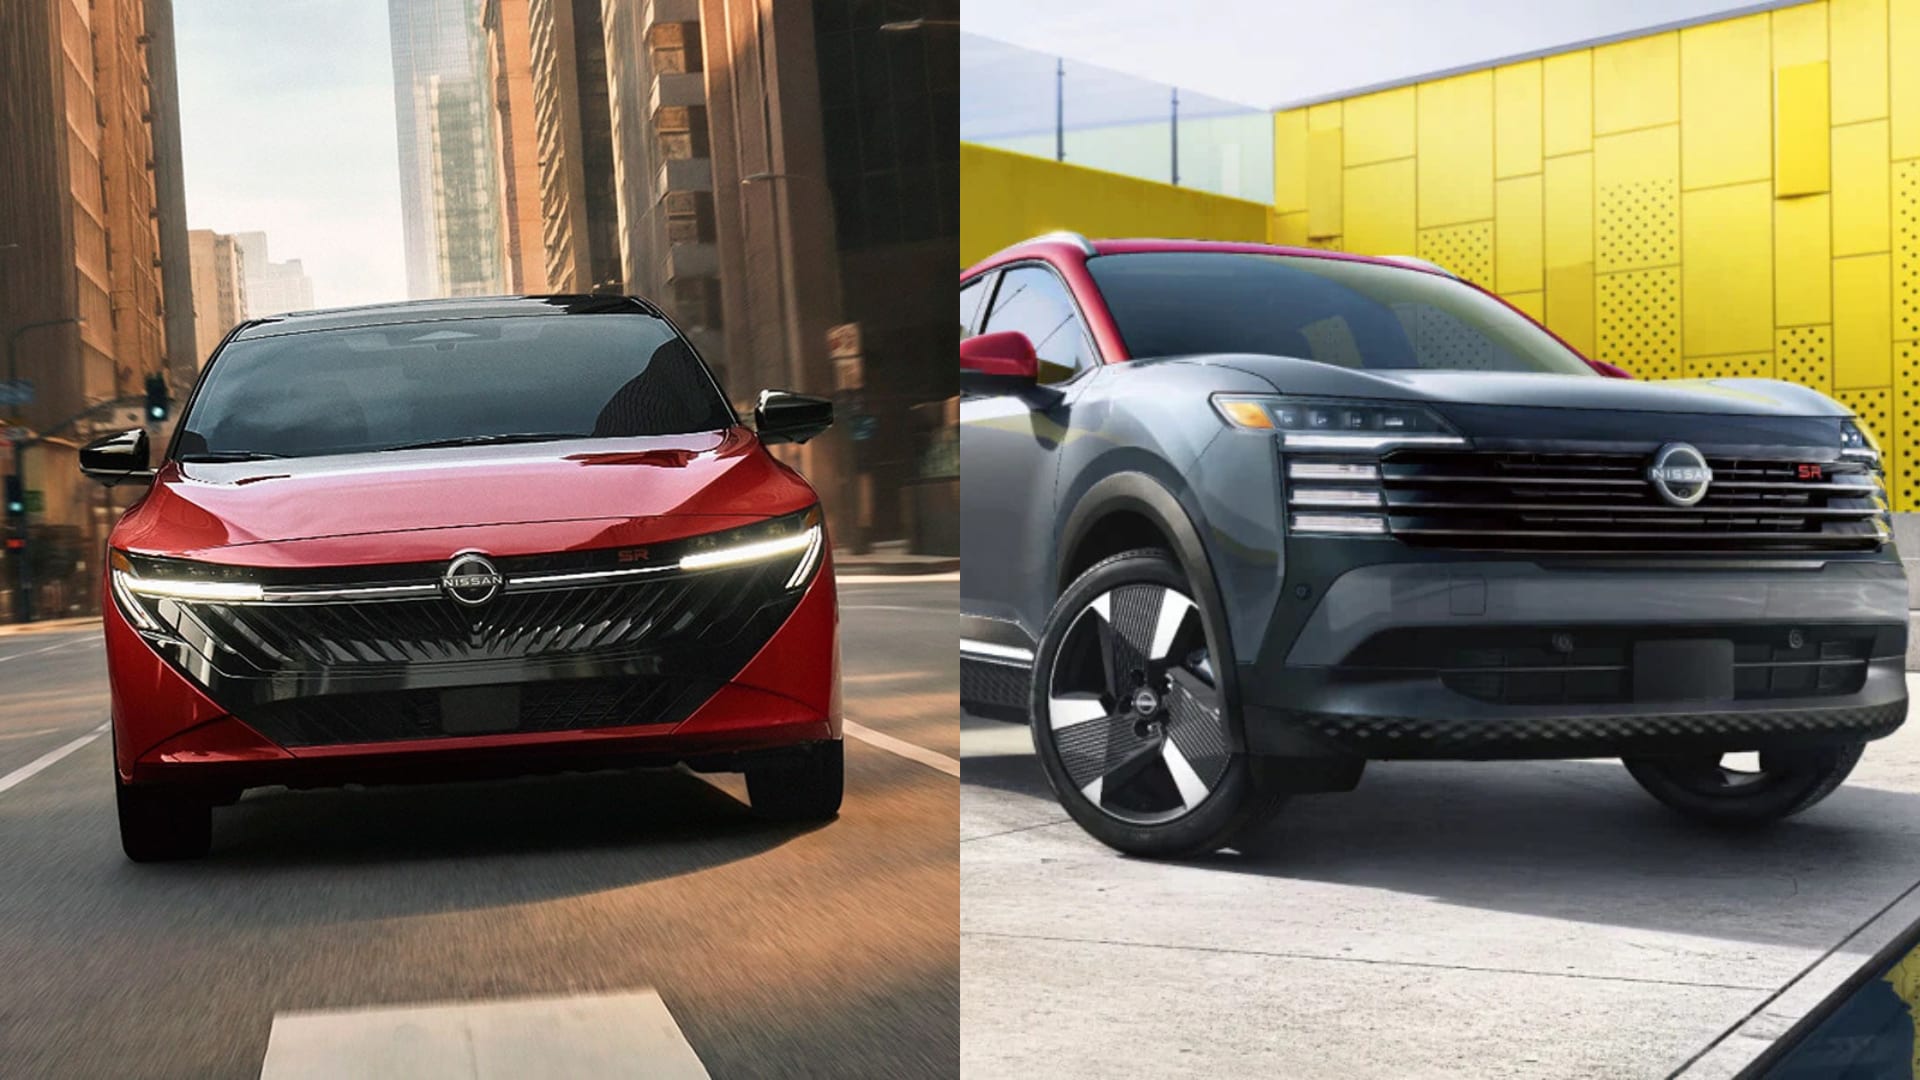
The 2026 Nissan Sentra starts at about $22,600, and the Kicks starts right around $22,730, landing them comfortably in the $400 to $600 range on a standard 60-month to 72-month loan with a reasonable down payment.
The Sentra just got a full redesign for 2026, with a new interior, available dual 12.3-inch displays, and fuel economy up to 38 mpg on the highway, which matters a lot for Phoenix commutes.
The Kicks trade a little bit of that efficiency for more cargo room and a higher seating position.
The choice between the two usually comes down to whether you want a sedan or a small SUV, not price.
Getting Closer to $400: Pre-Owned and Certified Pre-Owned Options
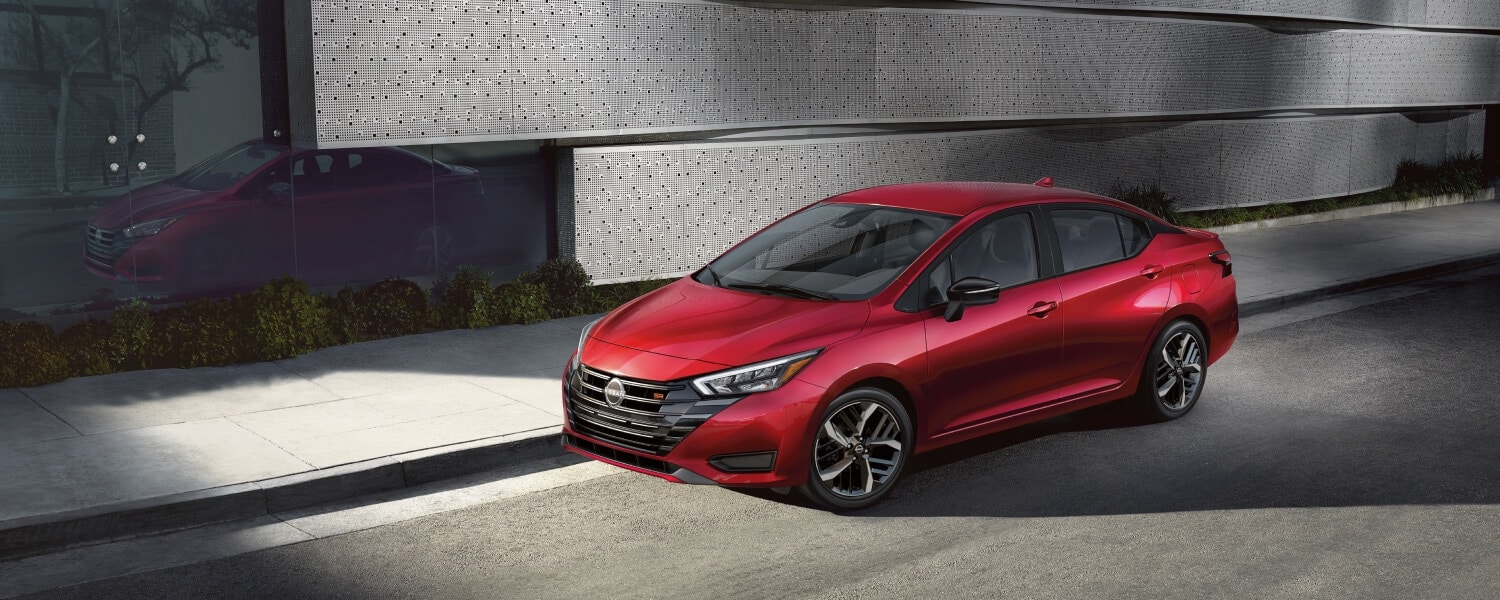
If the goal is landing closer to the $400 end of the range, a pre-owned vehicle may be the most direct path. Depending on current inventory, a late-model Versa, Sentra, Kicks or Altima may reduce the amount you need to finance while still providing many of the comfort, technology and safety features you want.
For buyers who want more vehicle without sending the payment substantially higher, Coulter Nissan's Certified Pre-Owned inventory is worth a serious look. A Certified Pre-Owned Rogue or Altima may fit the same general monthly budget as a new compact model while providing additional space, features and factory-backed warranty coverage.
Related: Which Nissan Models Last the Longest?
What Pushes You to $600
At the top of the range, a new Sentra SR or SL trim, a Kicks with a few added packages, or a lightly used Rogue all become realistic options, especially with a trade-in applied toward the down payment. This is also where term length starts to matter more than the sticker price. Two buyers financing the same Rogue can end up $150 apart on their monthly payment depending on whether they choose a 60-month or 72-month term, so it's worth running the numbers both ways before deciding.
Related: Why buy from Coulter Nissan?
The Variables That Actually Move Your Payment
Down payment size, loan term, interest rate, and trade-in value all shift where a car lands in this range, sometimes more than the car's price does. A stronger trade-in or a slightly longer term can move a Rogue from the top of the range down to the middle, while a shorter term can push even a Versa payment closer to $500. This is exactly the kind of math that's easier to walk through with a finance team than to estimate on your own because incentives and rates shift month to month.
Related: How to Get the Best Price for Your Trade-In
At Coulter Nissan in Surprise, the finance team can run these scenarios side by side so you can see exactly what a $400 payment buys versus a $600 payment, and what happens in between. No guesswork, just real numbers for real budgets.
Related: When Do Cars Drop in Price? The Insider's Guide to Timing Your Nissan Purchase
This, too: 2026 & 2027 Nissan Models Guide
FrequentlyAsked Questions
What car can I get for $500 a month?
Depending on your down payment and loan term, $500 a month typically covers a new Nissan Sentra, Kicks, or Versa, or a Certified Pre-Owned Rogue or Altima.
Is $600 a month too much for a car payment?
Financial experts generally recommend keeping total car costs, including insurance, under 15 to 20 percent of monthly take-home pay. Whether a $600 car payment is affordable depends on your take-home income, existing debts and other transportation expenses. Remember to budget for insurance, fuel, registration and maintenance in addition to the monthly loan payment.
Does a bigger down payment lower my monthly payment significantly?
Yes. A larger down payment reduces the amount you need to finance, which generally lowers the monthly payment and total interest paid. The exact difference depends on the vehicle price, interest rate and loan term.
Can I apply for financing before visiting the dealership?
Yes, you can apply for financing online before visiting. The finance team can then help you review available loan options and determine which vehicles may fit your monthly budget.